Springer Nature
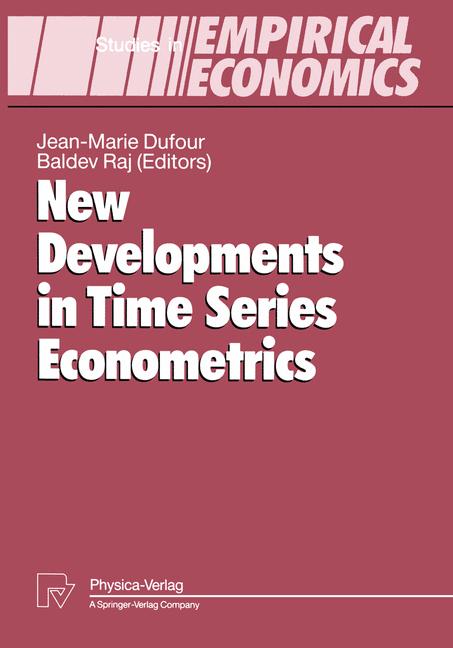
New Developments In Time Series Econometrics
Miglior prezzo disponibile
106,99€
Springer Nature · Spedizione gratuita
VISAPayPal
Prezzi aggiornati
Specifiche
MarcaSpringer Nature
CondizioneNuovo
Descrizione
This book contains eleven articles which provide empirical applications as well as theoretical extensions of some of the most exciting recent developments in time-series econometrics. The papers are grouped around three broad themes: (I) the modeling of multivariate times series; (II) the analysis of structural change; (III) seasonality and fractional integration. Since these themes are closely inter-related, several other topics covered are also worth stressing: vector autoregressive (VAR) models, cointegration and error-correction models, nonparametric methods in time series, and fractionally integrated models. Researchers and students interested in macroeconomic and empirical finance will find in this collection a remarkably representative sample of recent work in this area.
Storico prezzi
Ricevi una notifica se il prezzo scende
Ti invieremo un'email quando il prezzo di questo prodotto diminuirà.
- Aggiornamenti dei prezzi in tempo reale
- Oltre 50 negozi monitorati
- Avvisi gratuiti di calo prezzo
- Solo negozi verificati
Avvisami quando il prezzo scende sotto: 106,99€
Prodotti simili
Una selezione di prodotti che potrebbero interessarti. Guarda tutti
 Time Series Econometrics
85,59€
 Current Developments In The Interface: Economics, Econometrics, Mathematics
53,49€
 Recent Developments In Bayesian Econometrics And Their Applications
139,09€
 Econometrics, Finance, And Time Series Analysis
42,79€
 Econometrics Of Short And Unreliable Time Series
106,99€
 New Directions In Time Series Analysis
106,99€
 Recent Developments In Time-Frequency Analysis
106,99€
 New Directions In Spatial Econometrics
53,49€