Springer Nature

Separating Information Maximum Likelihood Method For High-Frequency Financial Data
Miglior prezzo disponibile
59,99$
Springer Nature · Spedizione gratuita
VISAPayPal
Prezzi aggiornati
Specifiche
MarcaSpringer Nature
CondizioneNuovo
Descrizione
This book presents a systematic explanation of the SIML (Separating Information Maximum Likelihood) method, a new approach to financial econometrics. Considerable interest has been given to the estimation problem of integrated volatility and covariance by using high-frequency financial data. Although several new statistical estimation procedures have been proposed, each method has some desirable properties along with some shortcomings that call for improvement. For estimating integrated volatility, covariance, and the related statistics by using high-frequency financial data, the SIML method has been developed by Kunitomo and Sato to deal with possible micro-market noises. The authors show that the SIML estimator has reasonable finite sample properties as well as asymptotic properties in the standard cases. It is also shown that the SIML estimator has robust properties in the sense that it is consistent and asymptotically normal in the stable convergence sense when there are micro-market noises, micro-market (non-linear) adjustments, and round-off errors with the underlying (continuous time) stochastic process. Simulation results are reported in a systematic way as are some applications of the SIML method to the Nikkei-225 index, derived from the major stock index in Japan and the Japanese financial sector.
Storico prezzi
Ricevi una notifica se il prezzo scende
Ti invieremo un'email quando il prezzo di questo prodotto diminuirà.
- Aggiornamenti dei prezzi in tempo reale
- Oltre 50 negozi monitorati
- Avvisi gratuiti di calo prezzo
- Solo negozi verificati
Avvisami quando il prezzo scende sotto: 59,99$
Prodotti simili
Una selezione di prodotti che potrebbero interessarti. Guarda tutti
 Separating Information Maximum Likelihood Method For High-Frequency Financial Data
44,99$
 Econometrics Of Financial High-Frequency Data
199,99$
 Risk Estimation On High Frequency Financial Data
54,99$
 Modelling And Forecasting High Frequency Financial Data
84,99$
 Method For High-Efficiency Data Compression And Transmission Of Vehicle Measurement Data Through Mob
119,99$
 13.56Mhz Industrial Rfid Reader Writer For Agv Reading Location Information High Frequency Rfid Senssor
455,45$
 RDC50 5.7 Inch Gnss Antenna High Precision Gis Information Collection Gis Data Collector Terminals For Land Resources
1243,67$
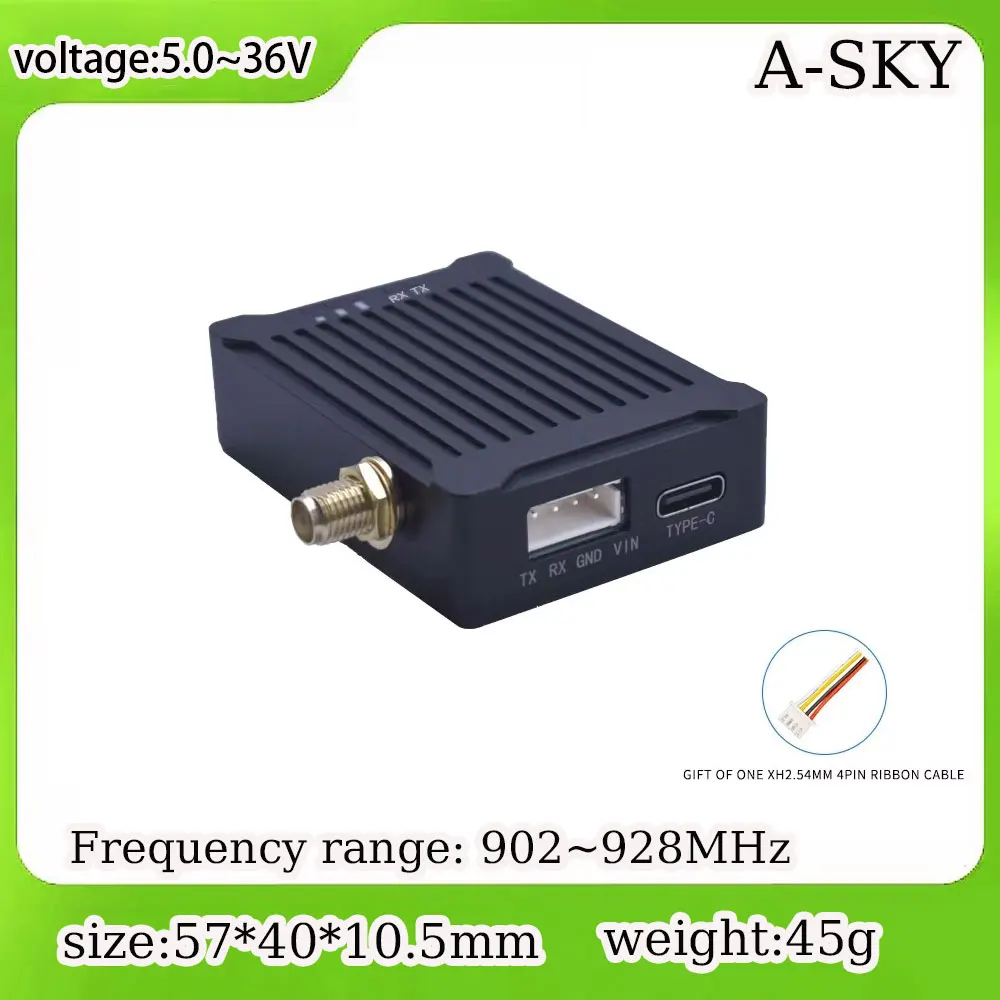 Long-Range Data Link System 60Km Maximum Range With 902-928Mhz High-Precision Rf Link For Industrial-Grade Pixhawk Communication
228,37$